If hail hits your roof, here is how a claim usually goes in Oklahoma, step by step, with the rules the Oklahoma Insurance Department points homeowners to. Our part is the roof: a free inspection, photos of the damage and a detailed photo report sent to you, and we meet your adjuster and inspect the roof together.
Your own policy is the final word. Keep it handy, or ask your agent, as you read.
- Stop the waterCover a leak and keep the receipts.
- Take photosBefore anything is moved or thrown away.
- Get the roof inspectedAnd get the photos.
- Contact your insuranceAsk what they need from you.
- The adjuster visitsNo permanent repairs before that.
- Watch the deadlinesYour policy and state law set them.
1. Stop the water first
If hail broke through and water is getting in, cover it. The Oklahoma Insurance Department tells homeowners to make the repairs needed to prevent further damage, such as covering leaking roofs, broken windows and holes. Save every receipt, including for those temporary repairs, since your policy might cover them.
If your roof is leaking, call us and we’ll tarp it to keep the water out until it can be repaired. Our page on emergency roof repair and tarping has what to do in the meantime.
2. Take photos before anything changes
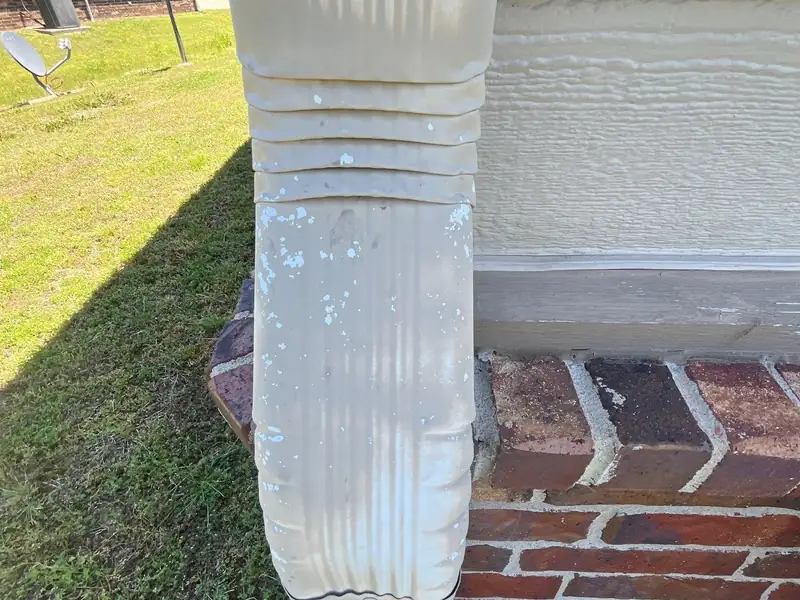
Take plenty of photos or videos of the damage, and don’t throw anything away unless your insurance company tells you to. Both come straight from the Insurance Department’s list.
You don’t need to climb on the roof for this. From the ground, photograph dents in the gutters, downspouts and window screens, and anything else the hail marked. Our guide on how to tell if hail damaged your roof shows what to look for.
3. Have the roof inspected and photographed
The Insurance Department’s advice is to have your roof inspected by a trusted roofing contractor before you contact your insurance company or agent.
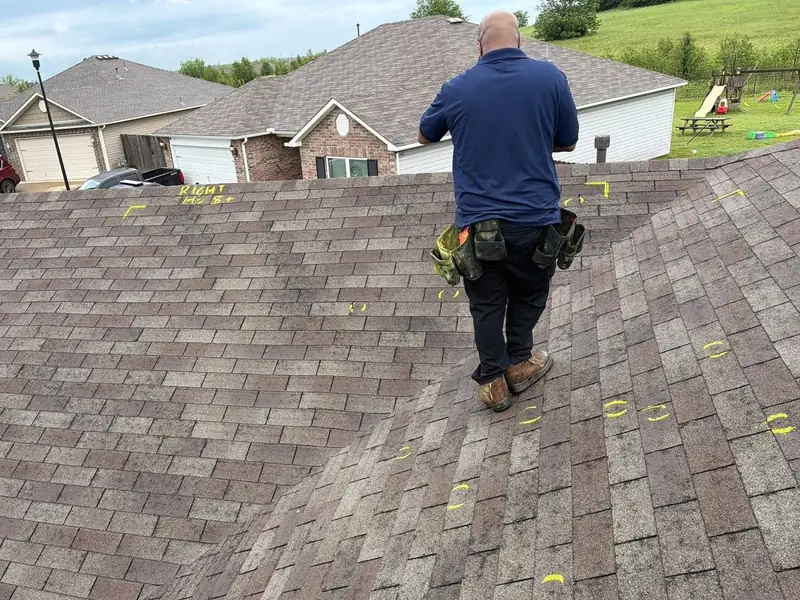
That part is ours. We inspect the roof for free, circle every hail hit we find in chalk, photograph the damage slope by slope and send you a detailed photo report. You see the same photos we see. Here’s what we check on a free roof inspection, and what we do after a storm.
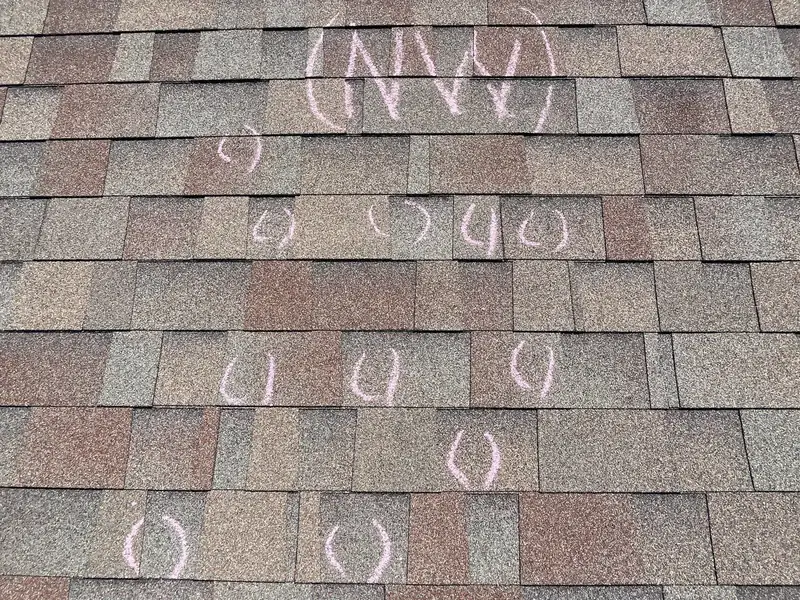
Think hail hit your roof? The storm inspection is free.
4. Contact your insurance company or agent
When you call your insurance company or agent, the Insurance Department suggests asking what forms, documents and information they need from you to process the claim.
Worried about your premium? The Insurance Department’s FAQ says that by law, a company can’t cancel, non-renew or raise the premium on a homeowner’s policy that has been in effect for more than 45 days solely because you filed a first claim on it. That protection covers a first claim only.
5. The adjuster looks at the roof
After you file, the insurance company usually sends an adjuster to look at the damage. We meet your adjuster and inspect the roof together. If something’s missing from the insurance estimate, we document it and send it in.
Until then, hold off on permanent repairs. The Insurance Department says not to have permanent repairs made until your insurance company has inspected the property and you’ve reached an agreement with them on the cost of the repairs. Temporary repairs to stop more damage are fine, as in step 1.
This company will not try to sell you a roof if you don’t need one. Refreshingly honest!
6. Watch the deadlines
Two dates to check against your own policy.
- Up to 24 months to fileIf your policy sets a time limit for wind or hail damage to the roof, state law says it must let you file up to 24 months after the date of the loss when the damage wasn’t evident without an inspection (36 O.S. § 1250.5, Insurance Department Bulletin 4-2022).
- Often 6 months to finish the workThe Insurance Department reminds homeowners that replacement cost policies generally require the work to be completed within six months of the date of loss to receive the replacement cost payments that were withheld. Check your policy for your own deadline.
Not sure when the hail was? Our list of recent hail dates around Tulsa and Claremore links to the National Weather Service reports.
7. Choose your roofer with care
After a big storm, a lot of roofers knock on doors. A few of the Insurance Department’s tips for choosing a roofer (the full list is in its May 13, 2026 guidance, linked in the sources below):
- Check references and phone numbers.
- Check with the Construction Industries Board that the roofer is licensed and carries liability insurance.
- Never sign a contract with blank spaces, and keep a copy for your records.
We’re a licensed roofer, OK LIC #80007402 (opens in a new tab): on the state lookup, enter that number under Registration Number. Our office is at 1938 U.S. Route 66 in Claremore, and you can read our 195 Google reviews.
Who does what
Your part
- Contact your insurance company or agent and file the claim.
- Decide on the repair and the roofer.
Our part
- Inspect the roof for free.
- Photograph the damage and send you a detailed photo report.
- Meet your adjuster and inspect the roof together.
- If something’s missing from the insurance estimate, document it and send it in.
- Tarp a leak, and put on the new roof if you choose us.
Questions we hear about hail claims
Who files a hail claim, me or the roofer?
You do: you contact your insurance company or agent to start it. We inspect the roof for free, photograph any damage and send you a detailed photo report, and we meet your adjuster and inspect the roof together. If something’s missing from the insurance estimate, we document it and send it in.
Should I call my insurance company or a roofer first?
The Oklahoma Insurance Department’s advice in May 2026, after the April storms around Enid, was to have the roof inspected by a trusted roofing contractor first, then contact your insurance company or agent.
How long do I have to file a hail claim in Oklahoma?
Check your policy. If it sets a time limit for wind or hail damage to the roof, Oklahoma law says it must allow claims up to 24 months after the date of the loss when the damage wasn’t evident without an inspection.
Will filing a claim raise my premium?
Oklahoma law limits it for a first claim. The Oklahoma Insurance Department says a company can’t cancel, non-renew or raise the premium on a homeowner’s policy in effect for more than 45 days solely because of a first claim. Your agent can tell you how that applies to your policy.
Can I fix the roof before the adjuster comes?
Cover a leak to stop more damage, and keep the receipts. Hold off on permanent repairs until your insurance company has inspected and you’ve agreed with them on the cost.
Sources
- Oklahoma Insurance Department: insurance and recovery guidance after the Enid storms, May 13, 2026 (opens in a new tab)
- Oklahoma Insurance Department: Bulletin 4-2022 on House Bill 3495 and 36 O.S. § 1250.5, May 31, 2022 (opens in a new tab)
- Oklahoma Insurance Department: frequently asked questions, homeowners (opens in a new tab)
- Oklahoma Construction Industries Board: roofing contractor lookup (opens in a new tab)
This is general information, not legal or insurance advice. Your policy and your insurance company have the final word.